Top 5 reasons to take Life Insurance

No one likes to think about a time after they’ve gone, but life insurance could offer reassurance and comfort to you and your loved ones for this situation.
residential mortgage

Ready to start your process?

Enquire about a mortgage with our affordability form. No imprint on your credit score.

Will not affect credit score

Buying a new home

Life insurance enables you to be proactive about ensuring those you care for can meet those financial commitments after you’ve gone. If you die before your mortgage is repaid, then the responsibility to complete payments falls to your loved ones. 

Just married

If you’ve recently become engaged or married, it can make life easier to know you are both covered if one of you were to die or to have a critical illness. Life insurance cover enables you to lift the burden of continued mortgage payments after you’ve departed.

Having a baby

The cost of raising children is expensive, even before factoring in considerations like education and university contributions.

Providing for your child to protect them against the unexpected is a way of giving yourself peace of mind and enjoy the present with them more fully.

Planning for a funeral

In 2019 the average funeral cost about £3,785.  Whole of life cover could help to pay off this cost. Contributions for this type of life cover tend to be smaller than others as the payout is significantly lower.

Inheritance tax

Another reason people may decide they need life insurance is inheritance tax. Inheritance tax has become a bit of a headache for those intending to leave money for their children once they die. Bills can run into tens of thousands of pounds, which can make a significant dent in your children’s inheritance. However, if you were to buy a life insurance policy that covered the tax bill, they could enjoy everything you intended them to receive.

Do I need life insurance?

No one likes to think about a time after they’ve gone, but life insurance could offer reassurance and comfort to you and your loved ones for this situation.

For most of us, life is a series of important milestones that may cause us to think about the future. Inevitably, when we think about our life and beyond, we can’t help but think of what may happen to the people we leave behind. It’s possible that your dependents or next of kin may become financially responsible for any of your outstanding debts or expenses like childcare costs, a mortgage or even funeral, medical or care costs.

Even if you have been careful with your finances and have no outstanding debts, you may simply wish to leave a legacy to your loved ones, help to contribute to the future cost of living for any dependents or give a small sum to help cover the cost of your funeral.

One way to determine whether or not you need life insurance is to consider what your financial obligations and contributions are and what the impact of this would be on your loved ones if you were no longer around. If your outgoings are not mitigated by a death in service policy, saleable assets or an income, investment, savings or pension plan then you may want to consider a life insurance policy.

You may have only just taken out a mortgage, meaning you have a lengthy financial obligation to fulfil. If you have children, you might want to ensure their future is secure with a financial sum.

As well as the essentials there are a surprising number of contractual expenses like the cost of running a home, other insurance policies, and raising a child to maturity which contribute to the cost of living and that you may overlook. If you find that you have little-to-no provision for your loved ones after you die, then life insurance might become a serious consideration.

What is the best cover for my needs?

There are three main types of term life insurance:

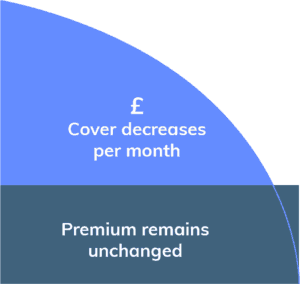
A decreasing term infographicDecreasing Life Cover

Decreasing cover life insurance is a type of cover that helps if you have a repayment mortgage or other sizeable reducing debt. The longer your cover is in place, the less is paid out. This is because your debts are also decreasing, and the insurance is there to help cover these payments. The monthly premiums for this type of policy may also be lower.

If you have an interest-only mortgage, you might be more interested in level-term life insurance. This is where payouts are fixed and the policy is in place for a pre-determined amount of time. The advantage of this kind of cover is that your family’s payout would be the same whether you died a year into your policy or a year before it expired.

The type of policy that you take out could be single – i.e. only covering you – or joint. A joint policy is usually cheaper than purchasing two single policies, but in most instances it only pays out once, if you make a claim you are no longer covered – the surviving partner would need to take out their own individual policy after that.

Two single policies can pay out upon the deaths of each policy holder and can take away the complexity in the unfortunate circumstance that the relationship comes to an end.
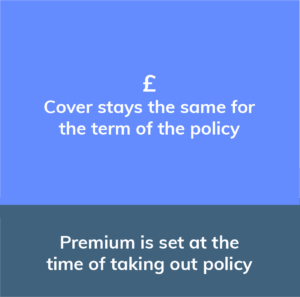
A level term policy infographicLevel Term Cover

Level cover term insurance are policies which pay out lump sums if you die within your agreed term. If you wish to leave a sum of money to your kids rather than pay off debts, then consider an increasing or level term policy.

Whole of Life Cover

Whole of life cover differs from term life in that there is no fixed length to the policy; it simply exists as long as you live and pays out upon your death. That doesn’t mean to say that you will pay indefinitely for a fixed sum of money though. You will stop paying premiums either after 30 years, on your 90th birthday or on the policy anniversary following your 90th birthday.

Trusts

You may also want to put your insurance policy into a trust. If the conditions of your trust are met, then this means that your assets no longer belong to you, but to the trust. In accordance with HMRC rules, your assets could then be exempt from inheritance tax. You would be able to decide how the trust is managed, for example whether your assets go straight to the beneficiary after your death or are retained by a trustee until your beneficiary reaches a certain age.

Trusts come with important legal implications, and should only be entered into after thorough discussion with an impartial legal or financial consultant. Once you have placed your policy in trust, it is very difficult to undo this, so being certain of what you are doing beforehand is crucial. There are several kinds of trust available, so it is also important to think long-term about how you want your money to be handled when considering this path.

How we can help?

According to Royal London, only 36% of uk consumers remember protection being mentioned by their mortgage’s adviser and 50% of households with mortgages don’t own a life/protection product.

Clever Mortgages believe that ALL is clients should be adequately protected when it comes to their mortgages and offer a FREE protection review with their Protection Specialist as part of the Mortgage service.

Whatever your budget our specialist team can build a protection package to meet your needs to contact us today on 0330 232 0285.

Clever Mortgages is now part of Oak Mortgages Limited.

Don’t worry, you’ll still be looked after by the same friendly, experienced team you know and trust. We’re here to guide you every step of the way on your mortgage journey.

👉 Discover more about us at www.oakmortgages.co.uk or see what our happy clients are saying on Google Reviews.

Posted on Google Google
G S profile picture
G S
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
From the very first contact through (what was a complex and hugely frustrating conveyancing process), to the day of completion, Oak Mortgages were the shining light that got us through. Sarah and her team were brilliant. They were responsive, caring, empathetic, knowledgeable, professional, and human at each and every stage. We are so grateful that we used Sarah and Oak Mortgages and highly recommend them to anyone wanting to guarantee that authentic, trustworthy approach from professionals who care. A top class act - 5 ⭐️⭐️⭐️⭐️⭐️
Posted on Google Google
DOBO and the Foodies profile picture
DOBO and the Foodies
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Awesome service, helped me at every step on a journey I never thought at 50 I could make! Sarah is amazing available whenever I needed her highly recommend
Posted on Google Google
Caoimhe Clarke profile picture
Caoimhe Clarke
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Thank you to Abby and the admin team at Oak Mortgages who have been fantastic in helping me secure a remortgage on my property. From my first phone call to Abby I was filled with confidence and the experience with the team was brilliant, especially when other companies involved were not so brilliant the Oak Mortgage team pulled out all the stops to make sure completion happened. I would highly recommend this company and will use their services in the future. Thank you again.
Posted on Google Google
Lisa Zuccotti profile picture
Lisa Zuccotti
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Excellent company to deal with , very efficient and caring ensured all our needs where met . Highly recommended.
Posted on Google Google
Reece Baird profile picture
Reece Baird
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
claire.geraghty Amazing lady, helped me all the way to the finish line! Highly recommend!
Posted on Google Google
graham draper profile picture
graham draper
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Excellent service and advice throughout the whole process making for a very straightforward experience with special thanks to Abby and Ashleigh.
Posted on Google Google
Ant profile picture
Ant
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Alex at Oak Mortgages has been an absolute life-saver. After being let down by a previous mortgage advisor who wanted me to take a massive risk with no guarantees, I contacted Oak Mortgages and was put in touch with Alex. ​Not only did he find me a mortgage with the exact same lender without having to take that risk, but he also got me accepted! His knowledge is top-notch, his communication is brilliant—he always picked up the phone and replied to emails super fast with regular updates. As a first-time buyer, Alex was hands-down the best part of the entire buying process. ​I am now happily settled in my new home, and I have Alex to thank for it. I will 100% be using Oak Mortgages again in the future (and hopefully Alex!). Thank you so much!
Posted on Google Google
Alannah McNaughton profile picture
Alannah McNaughton
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Abby Malcolm was fantastic. Work quickly to find me a great rate and explained everything I needed to know. Highly recommend her :)
Posted on Google Google
DanielaDany Zavaliche profile picture
DanielaDany Zavaliche
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
They are a very good and friendly team. I am very proud of them. Well done!
Verified by Trustindex
Trustindex verified badge is the Universal Symbol of Trust. Only the greatest companies can get the verified badge who has a review score above 4.5, based on customer reviews over the past 12 months. Read more
Skip to content